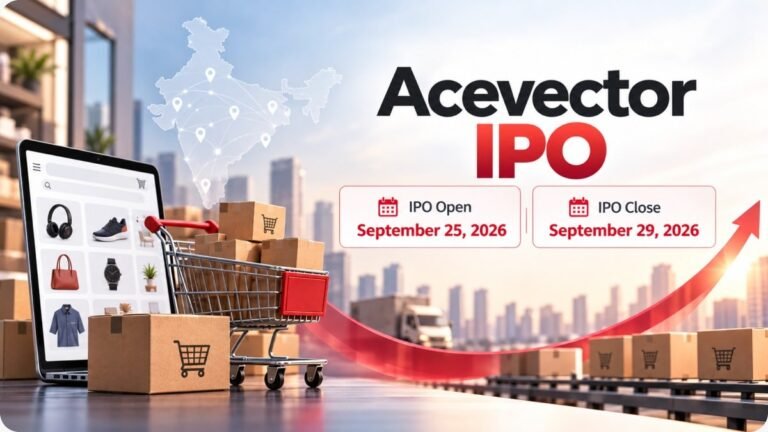
AceVector Limited is the holding company behind Snapdeal, India’s value-focused online marketplace founded by Kunal Bahl and Rohit Bansal, and the AceVector IPO marks the first time this restructured e-commerce group seeks public capital after years of operating as a private, investor-backed business.
The company files this ₹420 crore mainboard issue with a continuing loss track record — ₹45.51 crore net loss in FY2026, narrowed from ₹126.31 crore in FY2025 — and a retail allocation of just 10%, a consequence of SEBI’s framework that limits retail quota for loss-making companies.
This review covers the confirmed issue details, the company’s marketplace business model, the financial trajectory, valuation against listed e-commerce peers, the grey market signal, the use of proceeds, and what retail investors specifically need to verify before the bidding window opens on September 25, 2026.
AceVector IPO: Who Is AceVector Limited and What Does It Actually Operate?
AceVector Limited is the parent holding entity of the Snapdeal e-commerce marketplace — a value-segment online platform connecting buyers with sellers primarily in Tier 2, Tier 3, and rural India, competing in the same segment as Meesho and the price-sensitive cohort of Indian digital commerce.
The company’s registered office is at Okhla Industrial Area, Phase II, New Delhi, and its corporate website operates at acevector.com — a rebrand from the Snapdeal identity that reflects the group’s restructuring into a holding company architecture.
Co-founders Kunal Bahl and Rohit Bansal, both IIT Delhi graduates who previously worked at Microsoft, launched Snapdeal in 2010 as a daily deals platform before pivoting to an open marketplace in 2012-2013 when e-commerce growth accelerated.
The company previously held a stake in Unicommerce eSolutions Limited — a SaaS-based order management and warehouse management platform for e-commerce sellers — which separately listed on NSE and BSE in August 2024 and has since operated as an independent publicly listed entity.
AceVector’s current business after the Unicommerce separation centers on the Snapdeal marketplace: a platform earning commissions, seller service fees, and logistics revenue from the transactions of sellers on its platform.
The promoter group includes Kunal Bahl, Rohit Kumar Bansal, and Starfish I Pte. Ltd. — the latter a Singapore-incorporated entity likely representing the institutional component of the promoter-aligned holding structure.
AceVector IPO Date, Price Band and Issue Structure — Complete Details
The AceVector IPO opens for public subscription on September 25, 2026, and closes on September 29, 2026.
Anchor investor bidding takes place September 24, 2026, with the allotment finalised on September 30 and listing on BSE and NSE on October 5, 2026.
Confirmed Issue Details:
| Event | Detail |
|---|---|
| IPO Open Date | September 25, 2026 |
| IPO Close Date | September 29, 2026 |
| Anchor Bidding Date | September 24, 2026 |
| Allotment Date | September 30, 2026 |
| Refunds / Demat Credit | October 1, 2026 |
| Listing Date | October 5, 2026 (BSE & NSE) |
| Price Band | ₹30 – ₹32 per share |
| Face Value | ₹1 per equity share |
| Fresh Issue | ~₹287 crores |
| Offer for Sale | 4,15,62,500 equity shares (~₹133 crores at ₹32) |
| Total Issue Size | ~₹420 crores |
| Issue Type | Book Build — Mainboard |
The minimum retail application requires 468 shares at ₹14,976 per lot at the upper band of ₹32.
Market Lot Structure:
| Category | Lots | Shares | Amount (₹32) |
|---|---|---|---|
| Retail Minimum | 1 | 468 | ₹14,976 |
| Retail Maximum | 13 | 6,084 | ₹1,94,688 |
| S-HNI Minimum | 14 | 6,552 | ₹2,09,664 |
| S-HNI Maximum | 66 | 30,888 | ₹9,88,416 |
| B-HNI Minimum | 67 | 31,356 | ₹10,03,392 |
The investor reservation structure differs significantly from the standard mainboard allocation. Because AceVector is a loss-making company, SEBI mandates a higher institutional allocation: 75% to QIB, 15% to NII, and just 10% to Retail Individual Investors (RII). Retail investors applying to this IPO compete for a much smaller share of the total issue than in a typical profitable mainboard listing.
AceVector IPO Financials: Revenue Growing, But Losses Tell the Full Story
The AceVector IPO financials reveal a company on a meaningful improvement trajectory — but still firmly in loss territory at the time of listing.
Consolidated Financials (₹ in Crores):
| Period | Revenue | Expenses | PAT (Loss) | Total Assets |
|---|---|---|---|---|
| FY2024 | ₹384.74 | ₹427.67 | ₹(51.30) | ₹410.50 |
| FY2025 | ₹406.77 | ₹453.75 | ₹(126.31) | ₹558.09 |
| FY2026 | ₹537.67 | ₹575.22 | ₹(45.51) | ₹575.28 |
Revenue has grown from ₹384.74 crore in FY2024 to ₹537.67 crore in FY2026 — a 39.7% increase over three years, with a sharp acceleration to ₹130.90 crore additional revenue in FY2026 alone.
The FY2025 loss of ₹126.31 crore was the worst year in this reporting period — likely reflecting heightened marketing spend to defend market share as Meesho’s aggressive growth reshaped the value e-commerce segment. FY2026’s loss of ₹45.51 crore represents a 64% improvement, showing the cost rationalisation is working even as revenue expands.
FY2026 Valuation Metrics:
- EPS (Basic): ₹(1.32) — Negative
- NAV per share: ₹2.21
- RoNW: (59.54%) — Negative
- P/E Ratio: Not applicable (loss-making)
- Price-to-NAV at ₹32: approximately 14.47x
- Total Assets: ₹575.28 crore
The price-to-book of ~14.47x (at ₹32 vs NAV of ₹2.21) is the valuation figure investors must engage with in the absence of a meaningful P/E ratio. That multiple is high for a company still generating operating losses and depends entirely on the investment case that losses will continue narrowing toward profitability over the next 2-3 years.
AceVector IPO vs Listed E-Commerce Peers: The Revenue Scale Reality
The table below compares the AceVector IPO against three listed Indian e-commerce and digital commerce companies that represent the closest comparable peer group:
| Company | EPS (₹) | P/E Ratio | RoNW % | NAV (₹) | Revenue (₹ Cr) |
|---|---|---|---|---|---|
| AceVector Limited (IPO) | ₹(1.32) | N/A | (59.54%) | ₹2.21 | ₹537.67 |
| FSN E-Commerce Ventures (Nykaa) | ₹0.70 | 462.50x | 13.87% | ₹5.00 | ₹10,022.35 |
| Brainbees Solutions (FirstCry) | ₹(2.90) | N/A | (2.91%) | ₹90.71 | ₹8,547.94 |
| Meesho Limited | ₹(3.11) | N/A | (30.95%) | ₹9.25 | ₹12,626.35 |
The revenue gap is the most critical data point in this comparison. AceVector enters the public market at ₹537.67 crore in FY2026 revenue — approximately 5% of Meesho’s ₹12,626 crore and just under 6% of Nykaa’s ₹10,022 crore.
The scale disadvantage does not automatically disqualify AceVector as a listing candidate — Snapdeal’s value commerce positioning, operating cost structure post-restructuring, and narrowing loss trajectory represent genuine differentiators. However, investors allocating at ₹420 crore total market cap should recognise that achieving the revenue scale of listed peers requires multi-year compounding at the FY2026 growth rate of roughly 32% year-on-year.
Retail investors comparing AceVector with other ongoing IPOs in the same subscription window can read the German Green Steel IPO analysis on ipocontrol.in for a contrast with a profitable manufacturing IPO opening simultaneously in the same September 25-29 window.
AceVector IPO Use of Proceeds: Why ₹220 Crore Goes to Marketing
The fresh issue of ₹287 crore divides into three purposes, with the split revealing the company’s competitive priorities.
Use of Proceeds:
| Purpose | Amount (₹ Crores) |
|---|---|
| Marketing and business promotion — Marketplace business | ₹220.00 |
| Technology infrastructure costs — Marketplace business | ₹20.00 |
| Inorganic growth via acquisitions and general corporate purposes | Balance |
The ₹220 crore marketing allocation — representing 76.6% of the fresh issue — is the most important number in the entire prospectus for investors evaluating this IPO.
A company directing three-quarters of its IPO capital to marketing signals that customer acquisition cost remains the central constraint on its path to profitability — not manufacturing capacity, not working capital, not debt. Investors are essentially funding a large-scale advertising campaign with public capital, and the business case requires that this spend converts to sustainable GMV growth and eventually to seller revenue that exceeds the cost of the marketing that drives it.
The ₹20 crore technology allocation is comparatively modest, suggesting the existing Snapdeal platform infrastructure does not require major rebuilding — the core marketplace technology investment happened in the pre-IPO period.
The OFS component (4,15,62,500 shares at ₹32 = approximately ₹132.9 crore) flows to the promoter group, not the company. This means ₹132.9 crore of the ₹420 crore raised exits via selling shareholders — a factor investors should weigh alongside the fresh issue use-of-proceeds plan.
AceVector IPO GMP Today, Retail Quota and the Questions Investors Should Ask
The AceVector IPO GMP stands at ₹0 per share as of September 23, 2026 — no grey market premium reflects in informal pre-subscription dealer networks, unlike most other September 2026 mainboard listings.
A flat GMP on a loss-making e-commerce company opening in the same window as German Green Steel (GMP ₹15) and Runwal Enterprises (GMP ₹18) signals that grey market participants currently see no listing premium opportunity — and possibly anticipate listing at or below issue price.
Retail investors should register the 10% RII allocation specifically. In a standard oversubscribed mainboard IPO, retail allotment odds depend on the number of applications at the minimum lot. With only 10% of the issue available to retail — versus the standard 35% — the allotment probability per applicant is compressed regardless of overall subscription enthusiasm from QIBs and HNIs.
Subscription status updates will appear in real-time across all three categories on nseindia.com under primary markets and bseindia.com under the IPO section from September 25 onward.
The official RHP, containing full financial statements, related-party disclosures, the complete risk factor list, and precise use-of-proceeds breakdown, is available at sebi.gov.in — the only source that carries legal responsibility for disclosure accuracy.
Updates on subscription day data and listing day performance for this and other concurrent IPOs appear on Moneycontrol and Economic Times Markets.
Frequently Asked Questions
Q1: What is the AceVector IPO price band and why is the retail allocation only 10%? The AceVector IPO price band is ₹30 to ₹32 per equity share, with a face value of ₹1 per share. The retail allocation of 10% — instead of the standard 35% — applies because SEBI mandates a higher QIB portion (75%) for loss-making companies filing for listing. This regulatory framework exists to ensure that institutional investors with deeper due diligence capability take up the majority of shares in pre-profit companies before retail investors.
Q2: How does AceVector relate to Snapdeal, and has Unicommerce separated from the group? AceVector Limited is the holding company for the Snapdeal online marketplace business. The company co-founded by Kunal Bahl and Rohit Bansal restructured its group under the AceVector brand. Unicommerce eSolutions Limited — the order management SaaS platform that was previously part of the group — separately listed on NSE and BSE in August 2024, and AceVector’s current business focuses on the Snapdeal e-commerce marketplace operations distinct from Unicommerce’s operations.
Q3: Does the company’s loss history across FY2024, FY2025 and FY2026 make this IPO a bad investment? Loss history alone does not determine IPO investment merit — the trajectory matters alongside the loss quantum. AceVector reduced its net loss from ₹126.31 crore in FY2025 to ₹45.51 crore in FY2026, a 64% improvement, while revenue grew 32% to ₹537.67 crore. The case for the stock rests on whether this loss-narrowing trajectory continues toward profitability as marketing efficiency improves and the marketplace revenue base scales. Investors should read the RHP at sebi.gov.in for the company’s own projections and risk disclosures before deciding.
Q4: Can retail investors still apply to the AceVector IPO despite the 10% retail quota? Yes — retail investors can apply through UPI ASBA on any SEBI-registered broker platform. The 10% quota means fewer shares go to retail applicants overall, but eligible Retail Individual Investors can bid for up to 13 lots (6,084 shares) at a maximum application of ₹1,94,688. The allotment date is September 30, 2026, with shares credited to demat accounts on October 1, 2026. Allotment status checks use the MUFG Intime portal at in.mpms.mufg.com with the applicant’s PAN number.
Q5: Who is selling shares in the OFS — and how much does the promoter group sell? The offer for sale component is 4,15,62,500 equity shares, valued at approximately ₹132.9 crore at the ₹32 upper band. The proceeds from the OFS flow to the selling shareholders, not the company. As a result of this dilution, the promoter group’s stake drops from 65.90% pre-IPO to 47.40% post-IPO — falling below a majority position. The three promoters are Kunal Bahl, Rohit Kumar Bansal, and Starfish I Pte. Ltd., and investors should verify in the RHP which specific entities sell OFS shares and in what proportion.
Reading the AceVector IPO Before Bidding Opens
The AceVector IPO asks investors to price in a recovery thesis on India’s value e-commerce segment, backed by a brand with national recognition (Snapdeal) but backed by three years of losses and a revenue base that sits at roughly 4-6% of listed peers like Meesho and Nykaa.
The positive case is real: loss narrowing from ₹126 crore to ₹45 crore in one year, revenue growing at double-digit pace, and a simplified business structure post the Unicommerce separation that reduces management distraction. The use of ₹220 crore for marketing also signals genuine ambition to close the GMV gap with competitors — though that ambition runs directly through the use of public capital to fund continued operating losses.
The zero GMP, the reduced retail quota, and the peer revenue scale gap collectively indicate that this IPO prices primarily on institutional conviction about the e-commerce recovery thesis rather than near-term listing gains. Retail investors considering a bid should treat this as a longer-horizon allocation and read the complete RHP at sebi.gov.in before committing capital.
Disclaimer: This article is educational and informational only. It does not constitute investment advice or a recommendation to buy, sell, or hold any security. This site is not registered with SEBI as an investment advisor. Consult a SEBI-registered financial advisor before making any investment decisions.